Five stocks that trade on Korean golf
A simulator maker, its holding company, the owner of Titleist, a golf-apparel group and a rangefinder brand. GBR's equal-weight basket of listed golf companies is down 4.5 percent in a month, and the reasons say a lot about where the Korean game is going.
If you want to know whether the Korean golf business is healthy, you can wait for the biennial industry white paper, or you can look at five share prices on any trading day.
GBR tracks an equal-weight basket of five KRX-listed golf companies, rebased to 100 at the close 21 trading days ago. On 26 October 2026 it stood at 95.5, down 4.5 percent over the month. It is updated every morning on the home page and the numbers page shows every close. Here is what is in it, why each company matters, and what it has been telling us this autumn.
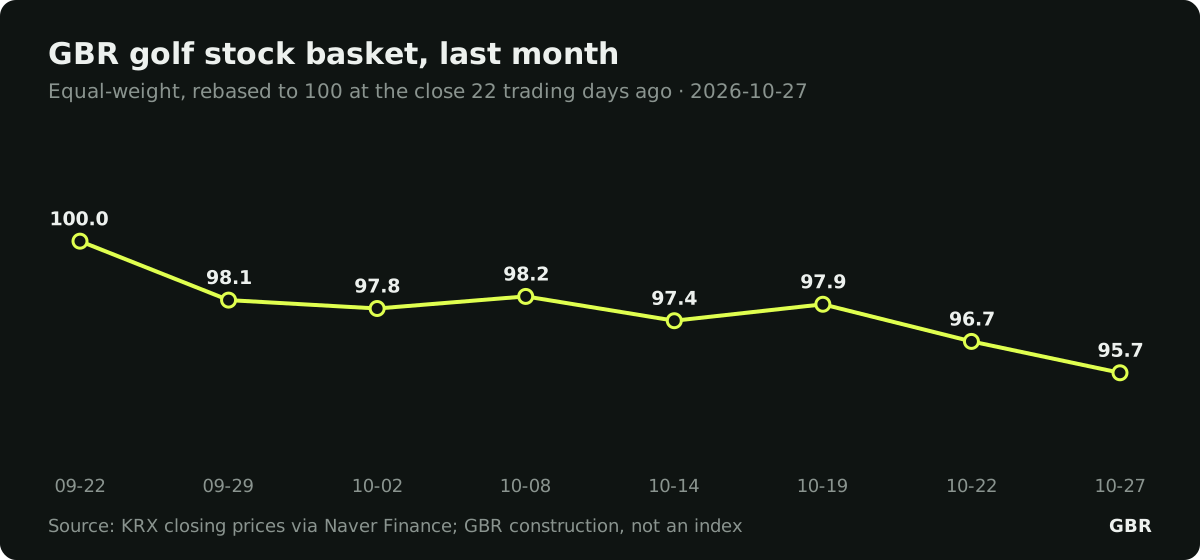 Five names, one line. Rebased to 100; KRX closes via Naver Finance.
Golfzon (215000)
The company behind the screen golf rooms that define the Korean game. Golfzon makes the simulators, licenses the software, sells to franchise owners and runs its own venues. Its results are a direct read on how many rounds Koreans are playing indoors and on whether its export push is working.
2025 was the year the two halves diverged. Revenue fell 26.4 percent to ₩409.9 billion and operating profit 29.8 percent to ₩96.5 billion, as fewer new golfers entered the game at home and the driving-range (GDR) business stayed weak. Overseas, though, revenue from its 14 foreign subsidiaries rose 33 percent in the first half of 2025, and by mid-2026 the company counted 4,385 locations worldwide, up from 3,696 a year earlier, with overseas sales growing for six straight quarters. The market's question is whether overseas growth can pay for itself: the foreign units have so far lowered group margins.
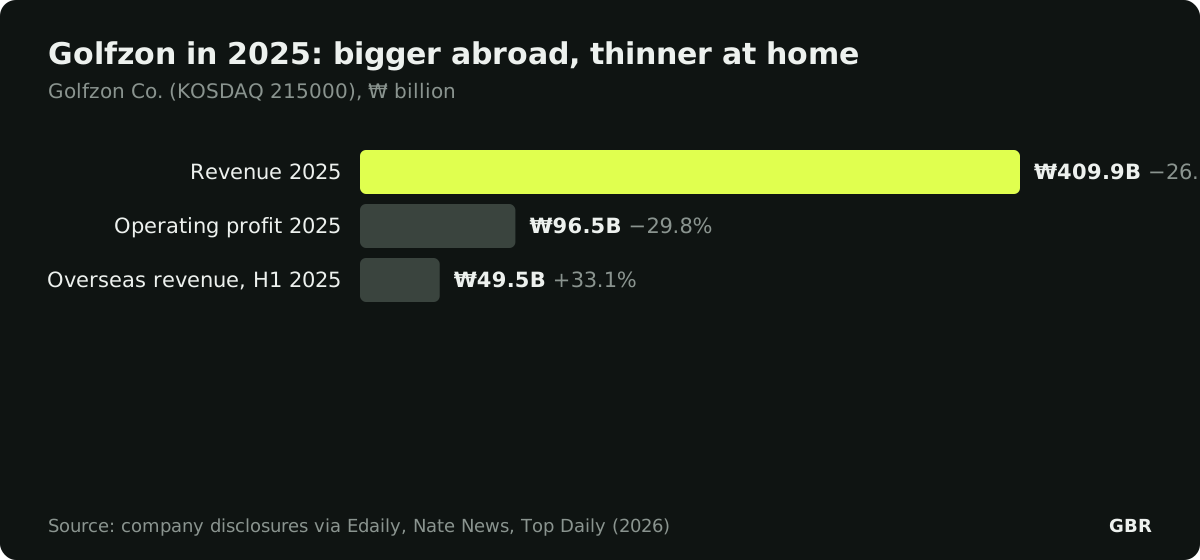 Smaller at home, bigger abroad. Company disclosures.
Golfzon Holdings (121440)
The holding company above Golfzon, formerly Golfzon Newdin Holdings, with interests in courses, practice ranges and other leisure businesses. Its consolidated 2025 revenue was ₩483.3 billion (−22.1 percent) and operating profit ₩68.1 billion (−29 percent). It moves with Golfzon but carries the group's real-estate and course exposure as well.
Misto Holdings (081660)
Until 2025 this company was known as Fila Holdings. It is the majority owner of Acushnet, the American parent of Titleist and FootJoy. That means the world's best-selling golf ball and the most-worn golf shoe on tour are controlled from Seoul. Misto's share price reflects global golf demand far more than the Korean market alone, which is why it is the basket's natural hedge: down 7.2 percent this month on the global cycle rather than anything Korean.
Crisfnc (110790)
A golf-apparel group whose brands include Pinggolf, Pearly Gates, Master Bunny Edition and St Andrews in Korea. Golf clothing is a large and unusually fashion-driven category here, and Crisfnc is one of the cleanest listed plays on it. 2025 revenue was ₩311.9 billion, down 5.8 percent, and profit collapsed as new-brand launches and the post-pandemic normalisation of golf fashion bit at the same time. The stock trades like what it is: a fashion company with golf as its theme.
VC Inc. (365900)
The company behind Voice Caddie, a brand of GPS rangefinders, launch monitors and golf wearables. It sits at the intersection of golf and consumer electronics, and exports a growing share of what it makes. Down 7.1 percent this month, it is the basket's most volatile name.
How to read the basket
The five companies cover the main ways money moves through Korean golf: playing indoors, playing outdoors, equipment, clothing and gadgets. Because the basket is equal-weight, no single company dominates it. When the number falls, investors are usually pricing in fewer rounds, weaker consumer spending or a slowdown abroad; when it rises, the opposite.
This month's 4.5 percent fall is the Korean story in miniature: the domestic game is normalising after the pandemic surge, the apparel boom is over, and the companies that are growing are the ones selling Korean golf to the rest of the world.
What to watch next
- Golfzon's overseas revenue share and whether the foreign units turn profitable.
- Acushnet's quarterly results, which flow straight into Misto Holdings.
- Whether Crisfnc's new brands produce the revenue recovery the company has promised for 2026.
Sources: Korea Exchange daily closing prices via Naver Finance (GBR basket, 26 Oct 2026); Golfzon Co. and Golfzon Holdings 2025 results via Edaily, Nate News, Top Daily and Hans Economy (2026); Edaily (English), Golfzon analyst note, August 2026; Crisfnc 2025 results via FnGuide and Fashion Insight. The basket is a GBR construction, not an official index, and nothing here is investment advice.